Hi there. Beggar King at your service.
Moving on to part 2 of personal balance sheet. Do read part 1 if you haven’t already done so.
In part 1 I explained how I calculate my monthly/yearly net income. Here I shall explain where I put them. Without further ado…
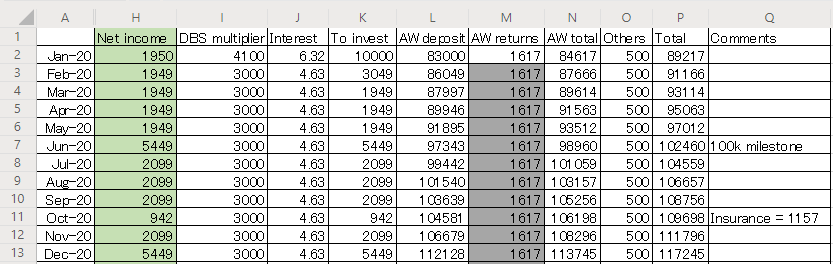
Savings Account
Most people probably put their money in savings account, such as DBS Multiplier or UOB One. It’s the most brain-dead way to earn some interests on your savings, and admittedly I was guilty of relying solely on them for the longest time. No longer do I endorse savings accounts, and I will explain that in my very next entry.
If net income DOES go entirely into savings account, savings account is simply “=savings account’s previous cell + net income“. If net income is column H and savings account is column I, it would be I3 = I2 + H3. I2 is the initial balance, which has to be input manually.
Else, just adjust the percentage of net income accordingly.
Savings Account Interest
In part 1, I explained net income, however that was only active income; income earned by trading your precious time. That means slaving working.
This is passive income; income earned by letting munny grow itself. Savings accounts ought to provide anywhere between 1% to 3% of passive income annually, which divided by 12 gives 0.0833% to 0.25% monthly. Singapore’s annual inflation rate is usually around 1-2%, so just having a good savings account is enough to beat inflation.
For this column, input this formulae “=savings account cell*interest rate/12″. For me it’s =I2*.0185/12, as 0.185% is what I get from DBS Multiplier. Then, add the result of this cell back to net income. With this, net income has become its final form (passive + active income).
Note : Interest compounds. 1.85% interest on $10000 over 10 years doesn’t simply give 10 times of $185, which is $1850. It actually gives 1.0185^10*$1000 = $2012, which is $162 more than $1850.
To Invest
This column is for munny to be invested. For me, this is equals to my net income, as I invest all 100% of my net income. If you wish to invest anything less than 100%, just input “=net income*0.x”, where 0.x is the percentage of income you wish to invest.
Investment
Add “To Invest” into this via formula “=investment’s previous cell + to invest“. Insert more columns as necessary.
I do passive investing, which is an investment strategy to maximize returns by minimizing buying and selling, via Autowealth. It is a robo-advisor, which is another a huge topic for another day. Currently almost all my munny are here.
There’s also stuff like Bitcoin and whatnot. Insert more columns as necessary.
Investment Returns
The passive income from investment, which comprises of gains (or losses) from investments, as well as dividends paid out. As of now, I got $2000 out of Autowealth in just 1.5 months. Will go into details when I write about Robo-advisors.
As there is no way to project returns from investments, I take the return from the end of the previous month for current and subsequent months.
Robo-advisors automatically reinvest dividends, so there is no need to add returns to net income.
Investment Total
This is simply investment + investment returns.
Other Money
This column is for all other places you put your munny. Namely :
- Cash in your wallet
- Foreign currency you exchanged in preparation for an overseas trip
- Deposits in digital wallets (Steam/Amazon/Youtrip)
For me, I use this wonderful app called Youtrip. It is a credit card with a foreign currency wallet which allows one to convert currency with no conversion fees and at close to real time exchange rate. As I shop from Amazon Japan and other Japanese online shops frequently, I keep $500 SGD worth of Japanese yen ready at all times. I do this by regularly checking the JPY/SGD forex and exchanging for JPY when it is weak against SGD. This allows me to always shop with yen exchanged at a really cheap rate. Youtrip is a topic for another day as well. There sure are a lot of topics to cover, aren’t there. 😮
It’s a good idea to keep this low, as the munny here isn’t making more munnys. No piggy banks, no stashing under pillows!
Total Savings
And finally here we are. Total savings is the sum of savings accounts, investment total, and other money. There you have it. This is your liquid net worth. There’s actually CPF as well but there’s no easy way to tap on it so it’s not exactly liquid.
Comments
This is just a column for any comments you may want to write down, such as overseas vacation dates or insurance premium payment date. Anything goes.
AND that is all! That was… long.
Personal Balance Sheet Summary
- If all incomes and expenditure are correctly inputted, and you stick closely to the plan, you will definitely get your projected savings.
- Set short term goals, and achieve them! You will be motivated to keep this going forever.
- If you fail to achieve a goal, it’s likely due to not adhering to expenditure, or perhaps due to some major unforeseen expenditure. Readjust expenditure and goal realistically.
- There are many places to put your savings. Don’t just keep them all in a bank. Start by investing a little. It is never too late to start. 🙂
- Remember, even if you can only save $10k a year, that’s still $100k in 10 years, and $300k in 30 years. That is enough to generate some seriously badass interests/returns. Possibly enough passive income for a comfortable retirement.
- Feel free to customise the balance sheet as you see fit. Mine is only there to serve as reference.

